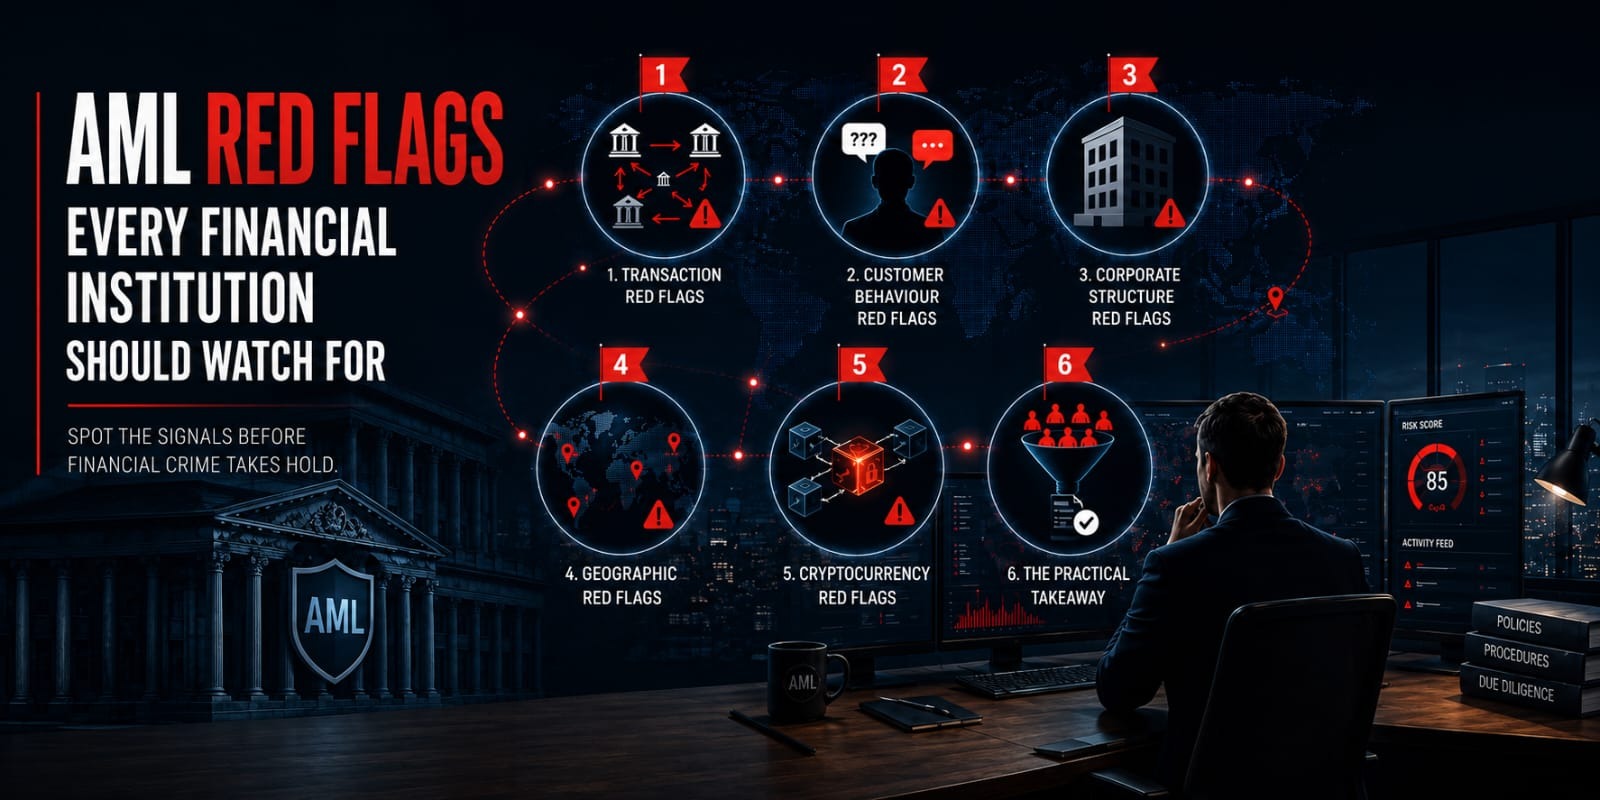
Most financial crime doesn’t announce itself. It moves quietly through ordinary-looking transactions, unremarkable accounts, and clients who appear entirely legitimate on the surface. What breaks it open is rarely a dramatic confession or a lucky tip. It’s a pattern of signals that, once recognized, makes the suspicious activity impossible to ignore. That’s what AML red flags are: the early warning system that gives financial institutions the chance to act before real damage is done. For institutions that take them seriously, they are genuinely one of the most powerful tools in financial crime prevention. Those institutions build the processes to identify, escalate, and act on them. Here’s a structured breakdown of what those signals actually look like across the categories that matter most. Read on to learn which AML red flags every financial institution should watch for.
Why AML Red Flags Are Worth Taking Seriously
Before getting into the specifics, it’s worth being clear about what AML red flags are and what they aren’t. A red flag doesn’t prove a crime has been committed. It identifies where closer scrutiny is warranted.
That distinction is important. It shapes how institutions respond and how investigators work with the information.
The practical value of a well-functioning red flag system is simple. It allows institutions to prioritize investigation resources toward the accounts and transactions that actually carry risk. The alternative is applying the same level of scrutiny across an entire customer base, which is neither practical nor effective.
The other thing worth understanding is that AML red flags are most powerful not as individual signals, but as converging patterns. A single indicator might have an innocent explanation. Two or three aligning around the same account or transaction tells a significantly different story.
AML Transaction Red Flags: Where the Money Tells the Story
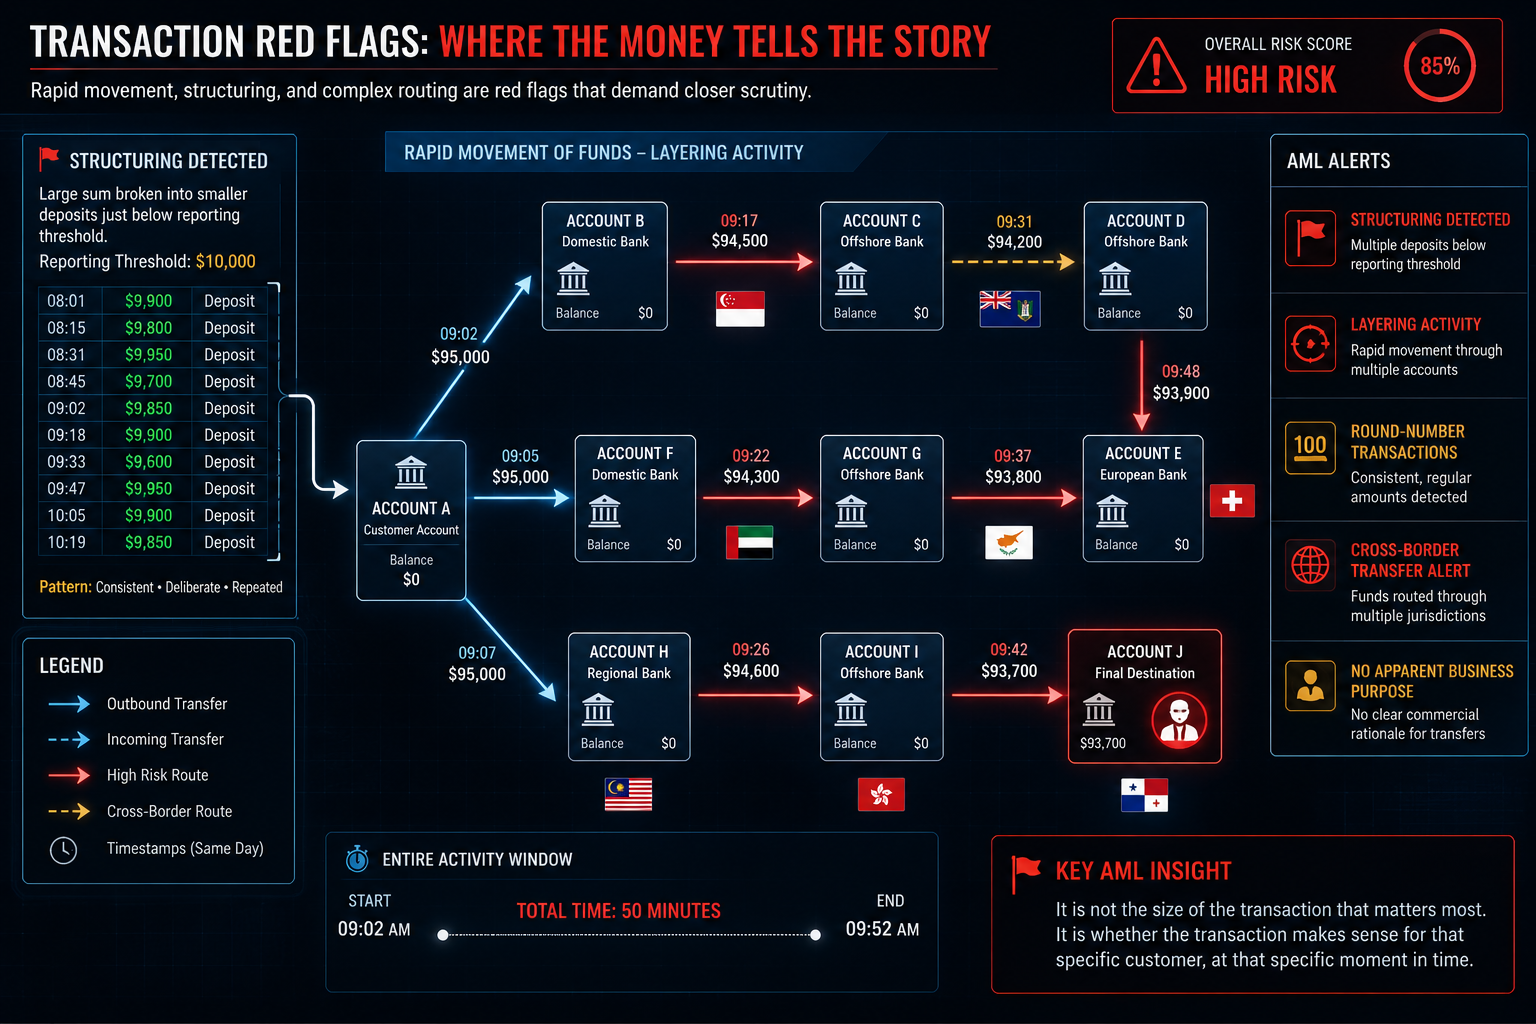
Transactions are where financial crime most reliably leaves traces. That is also where the clearest AML red flags tend to appear. Structuring is one of the most well-documented patterns. It means breaking large sums into smaller deposits that fall just below mandatory reporting thresholds. The amounts themselves may look unremarkable. The pattern is the flag: consistent, deliberate, and repeated.
Rapid movement of funds with no apparent business purpose is a reliable signal of layering activity. Money that arrives and leaves within hours, across multiple accounts, is not normal business behavior when no commercial logic connects the movement. It is the footprint of someone trying to put distance between funds and their origin.
Round-number transactions repeating at regular intervals are worth examining. Genuine commercial transactions are rarely this clean or this consistent. Regularity of this kind is a pattern, not a coincidence. These are classic AML red flags.
Wire transfers through unexpected jurisdictions or correspondent banks raise an obvious question when no clear commercial rationale exists: why this route? When there’s no answer that makes sense for that customer’s business, the routing itself becomes the flag. Experienced AML professionals apply one key insight here. The size of a transaction is not what matters most. What matters is whether the transaction makes sense for that specific customer, at that specific moment in time.
A transaction that would be unremarkable for one customer profile can be highly suspicious for another.
AML Customer Behavior Red Flags: When Something Doesn't Add Up
Some of the most telling AML red flags come not from the transactions themselves, but from how customers behave when questioned about them.
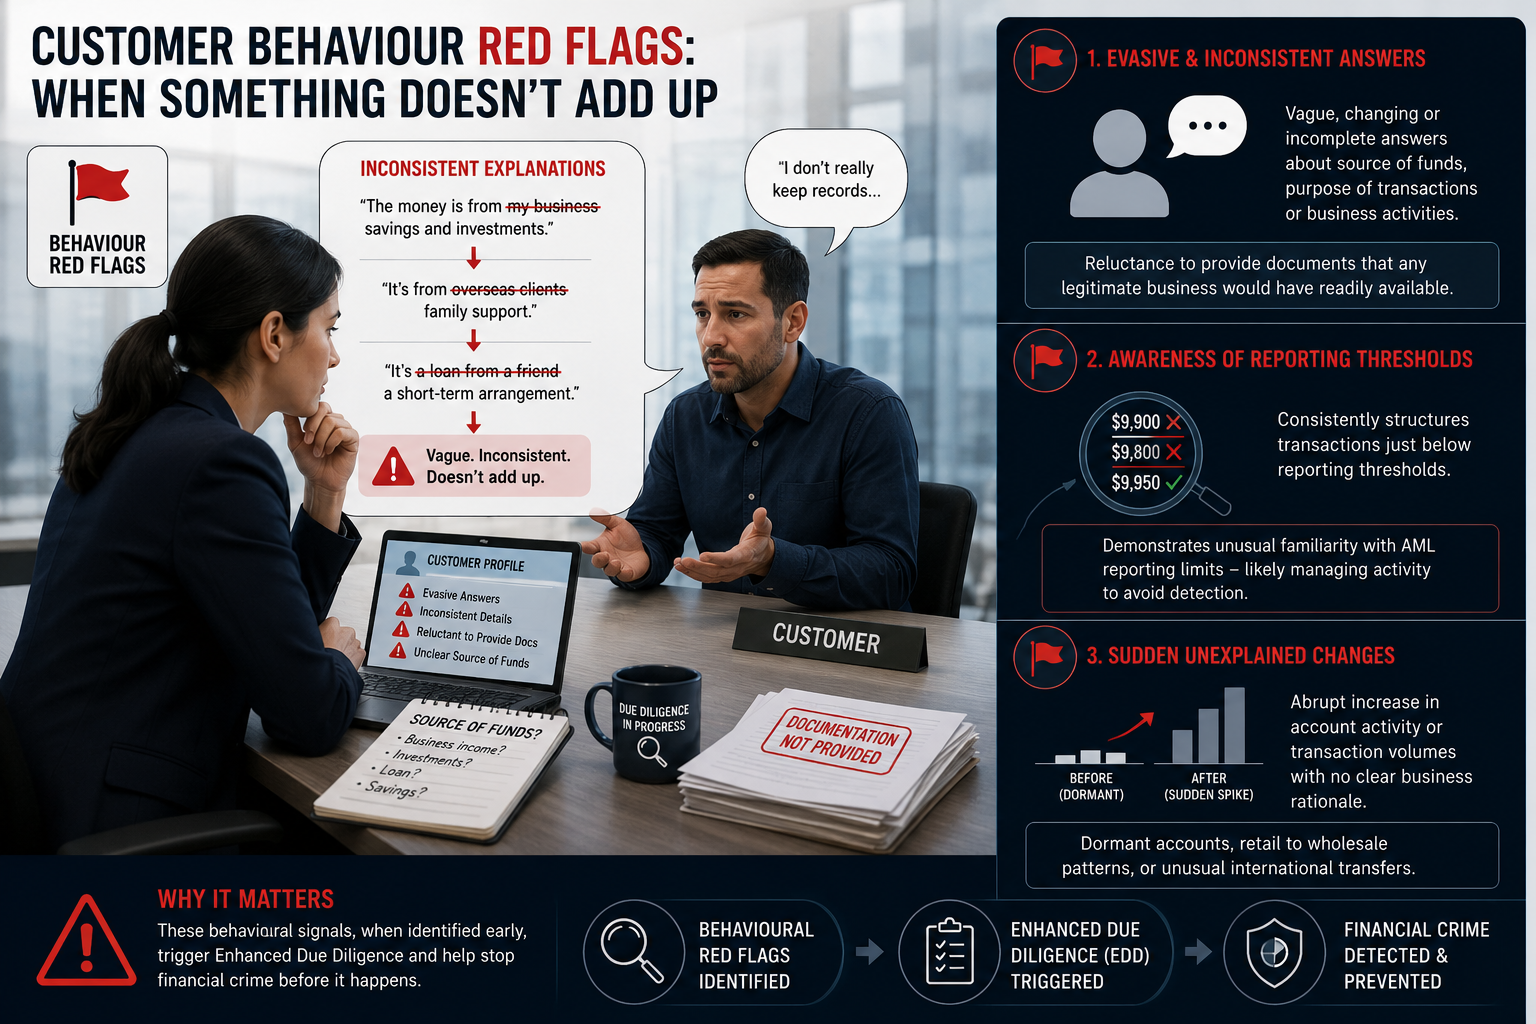
Evasiveness about source of funds, purpose of transactions, or the nature of a business is a consistent precursor to financial crime. This is rarely an outright refusal to answer, because that would be too obvious. Instead, it’s vagueness that shifts and changes under follow-up questions. It’s answers that don’t quite fit together. It’s reluctance to provide documentation that any legitimate business would have readily available.
Customers who appear unusually familiar with AML reporting thresholds are signalling something. Consider a customer who consistently structures their activity just below the reporting thresholds. If that customer also shows awareness of those thresholds in conversation, it is unlikely to be an accident. This is one of the clearest behavioral signals that an individual is not just conducting transactions. They are managing them specifically to avoid detection.
Sudden unexplained changes in account behavior warrant attention. Think of a dormant account that suddenly receives large international transfers. A retail customer’s activity may suddenly resemble a wholesale operation. Or consider a business account whose transaction volumes increase by an order of magnitude with no corresponding change in declared business activity. Normal accounts change gradually and for identifiable reasons. Abrupt, unexplained shifts in behavior are not normal.
These signals, caught early, are exactly what triggers the enhanced due diligence that brings financial crime to the surface before it completes.
AML Corporate Structure Red Flags: When Complexity Is the Point
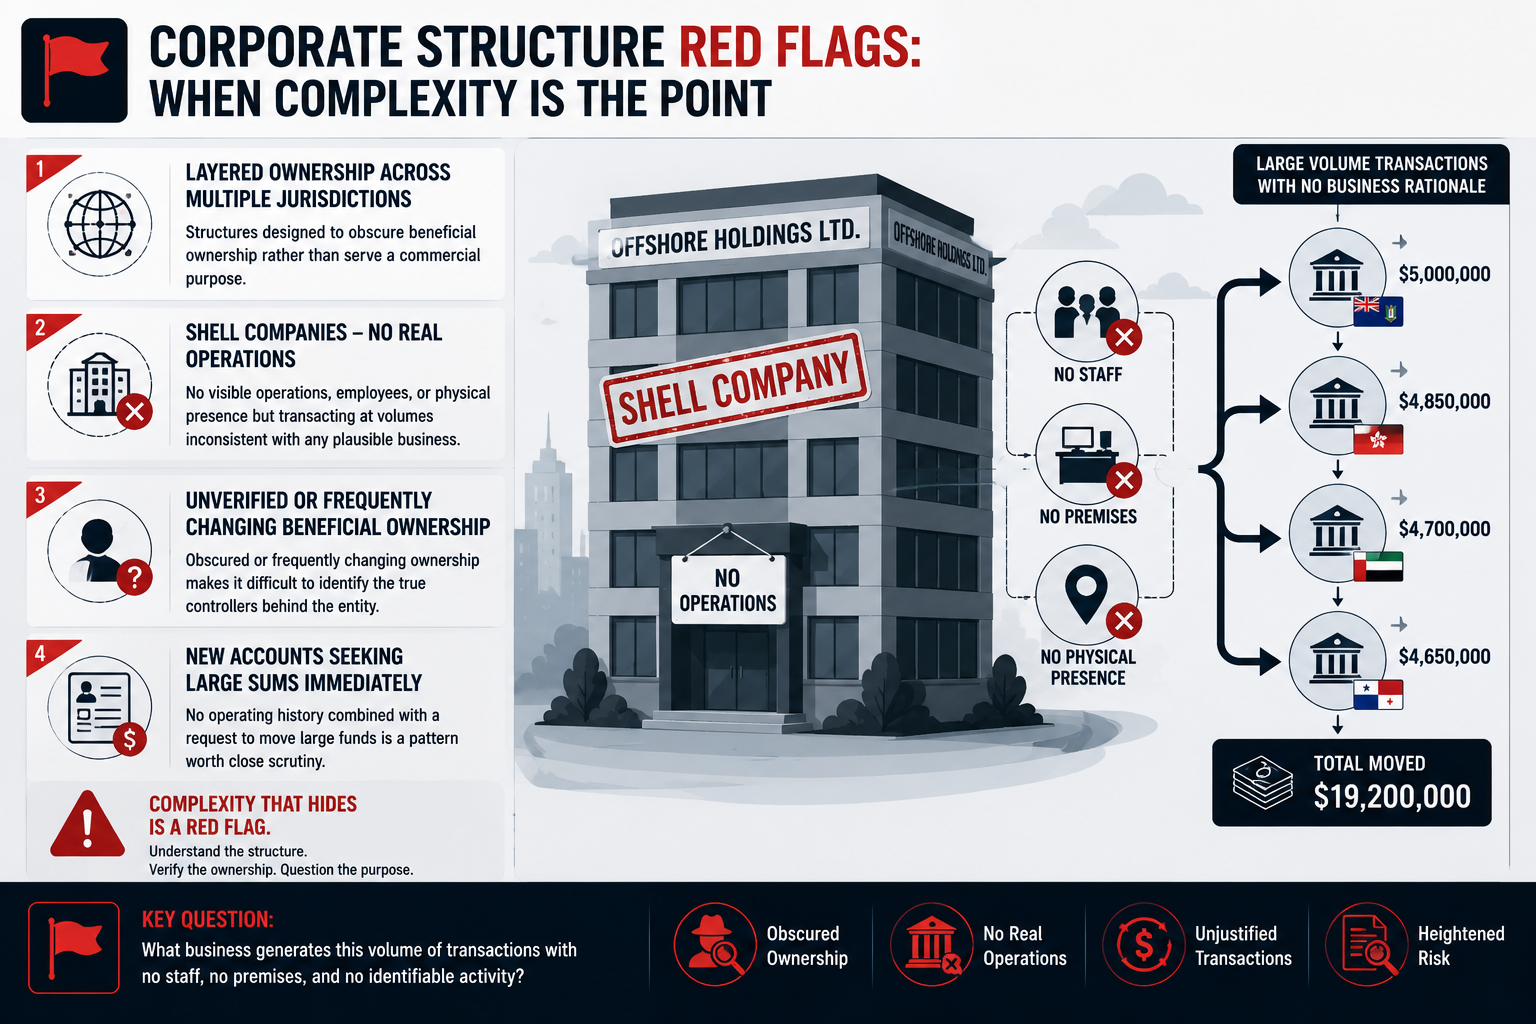
Legitimate businesses can have complex structures. But there’s a difference between complexity that serves a commercial purpose and complexity that exists specifically to obscure.
Ownership structures layered across multiple jurisdictions with no apparent commercial rationale fall into the second category. Sometimes a corporate structure appears designed to make beneficial ownership difficult to determine, rather than to serve any identifiable business function. That design is itself an AML red flag.
Shell companies are a well-established vehicle for money laundering. These are companies with no visible operations, employees, or physical presence that transact at volumes inconsistent with any plausible business activity. The question to ask is simple: what business generates this volume of transactions with no apparent staff, no premises, and no identifiable commercial activity?
Beneficial ownership that cannot be confirmed, or that changes frequently without clear explanation, is a significant concern. FATF’s international standards require financial institutions to identify and verify the beneficial owners of legal entities. This is where the connection between illicit funds and their true controllers is most often concealed. Our enhanced due diligence and UBO research targets exactly this gap.
New corporate accounts that seek to move large sums immediately, without any established operating history, combine two flags. Individually, each might be explicable. Together they represent a pattern worth scrutinizing closely.
Geographic AML Red Flags: When the Routing Doesn't Make Sense
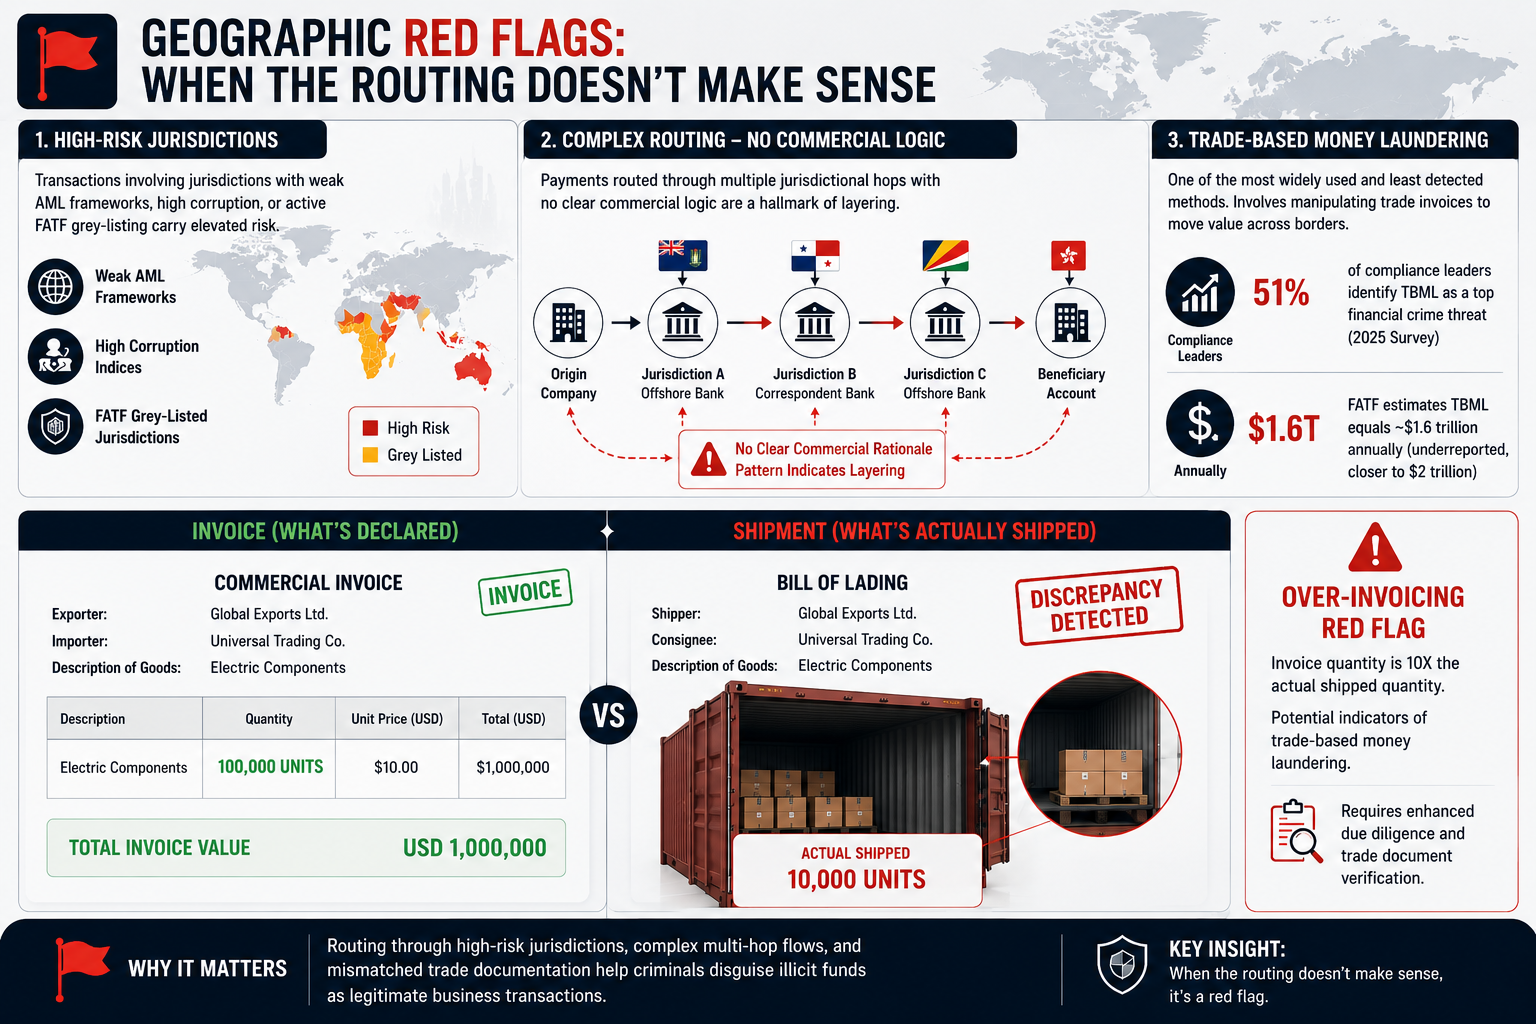
Geography matters in financial crime, not because crime is confined to particular regions, but because routing decisions reveal intent. Geographic AML red flags often show that intent first.
Transactions involving jurisdictions with weak AML frameworks, high corruption indices, or active FATF grey-listing carry elevated risk. This is not because everyone transacting in those jurisdictions is a criminal. It is because those environments offer less resistance to illicit flows. The presence of such jurisdictions in a routing pattern is a signal worth examining.
Payments routed through multiple jurisdictional hops with no clear commercial logic are a hallmark of layering. Consider funds moving from one country to another to another. If they pass through correspondent banks with no obvious commercial connection to the underlying transaction, they are following a path designed to obscure, not to transact.
Trade invoices that don’t match the goods being shipped sit in a category of financial crime that is both widely used and significantly underdetected. In a 2025 State of Financial Crime Survey, 51 percent of compliance leaders identified trade-based money laundering as one of their top financial crime threats. FATF estimates that trade-based money laundering accounts for roughly $1.6 trillion annually. That figure is already considered underreported, and some estimates place it closer to $2 trillion.
Over-invoicing and under-invoicing on international transactions is one of the most widely used and least detected laundering methods in operation today. Criminals inflate or deflate the stated value of goods to move funds across borders under the cover of legitimate trade.
The method persists because it embeds illicit flows within legitimate-looking trade transactions. As a result, detection depends on cross-referencing financial data with trade documentation. Many institutions are not yet doing this systematically. Our fraud and money laundering investigators regularly trace these trade-based flows.
Cryptocurrency AML Red Flags: The Newest Frontier
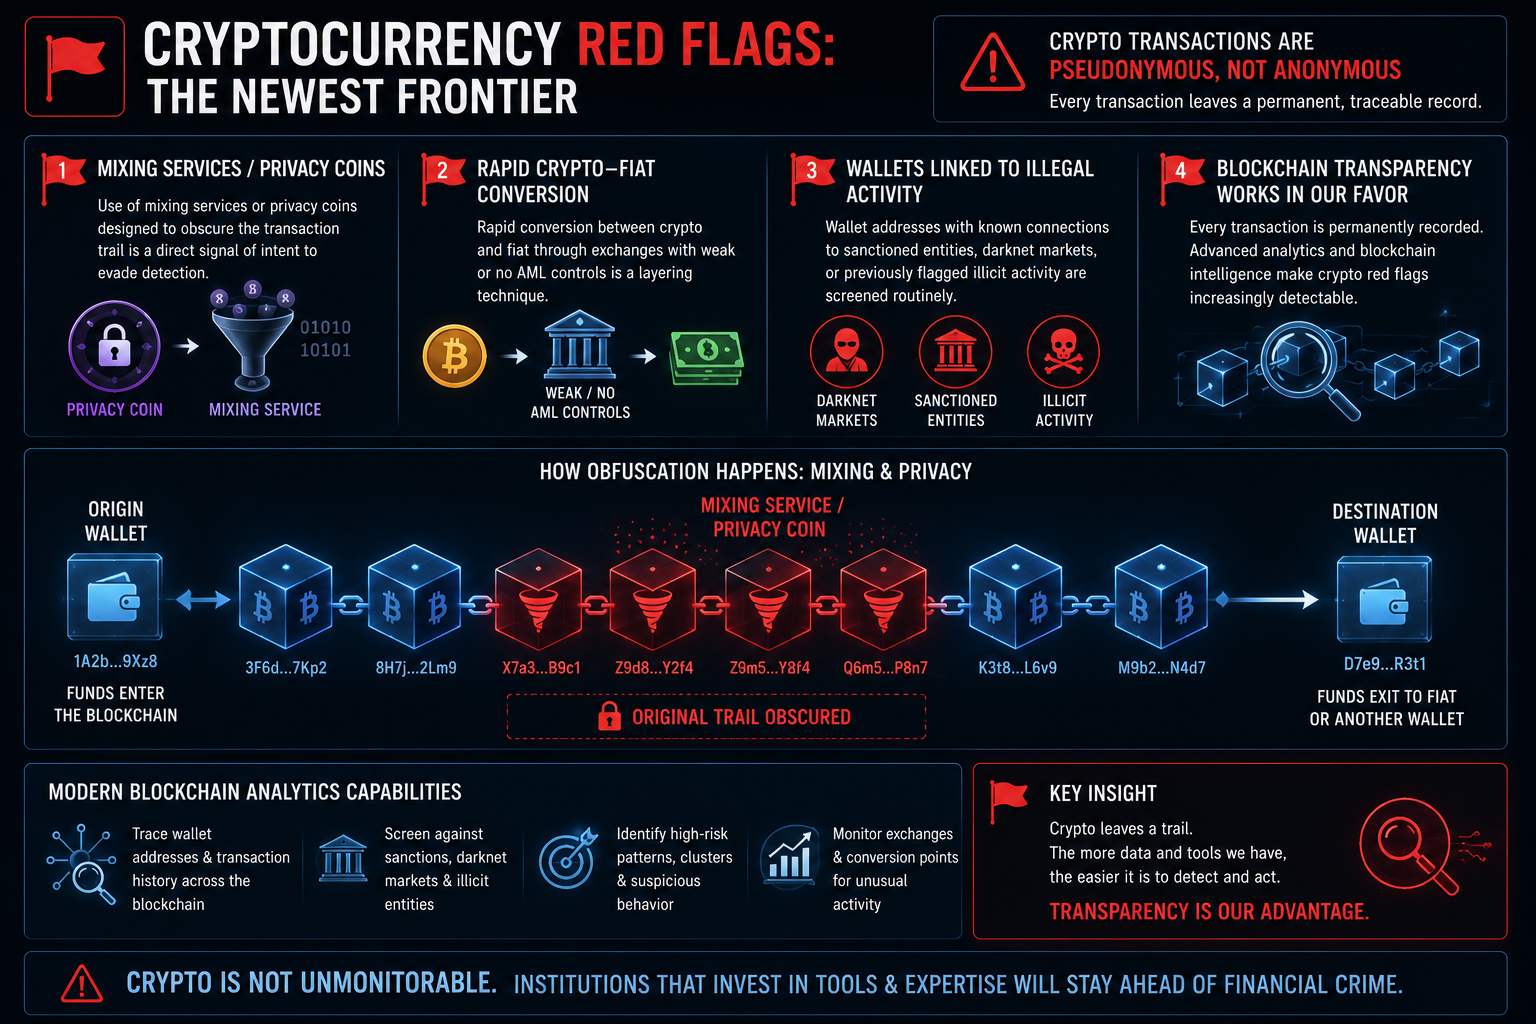
Cryptocurrency has introduced a new category of AML red flags that financial institutions are increasingly expected to understand and monitor. The good news is that the tools to do so are developing rapidly.
Use of mixing services or privacy coins specifically designed to obscure the transaction trail is a direct signal of intent to evade detection. While there may be legitimate privacy motivations for such tools in some contexts, their use in financial transactions involving institutions warrants scrutiny.
Rapid conversion between crypto and fiat through exchanges with weak or no AML controls is a layering technique. It uses the conversion process to break the link between the original funds and their destination in the conventional financial system.
Wallet addresses with known connections to sanctioned entities, darknet markets, or previously flagged illicit activity are now screened routinely by institutions with access to blockchain analytics tools. These tools allow institutions to screen wallet addresses and trace transaction histories in ways that were not possible even five years ago. Crypto red flags are increasingly detectable, not less so.
The trajectory here is encouraging. Every transaction on a blockchain is permanently recorded and publicly visible. This fundamental transparency means that the investigative tools available to institutions and investigators improve with every year.
Financial crime that moves through cryptocurrency leaves a trail. The institutions that invest in the tools and expertise to read that trail are significantly better positioned than those that treat crypto as an unmonitorable frontier. See how investigators follow crypto money in practice.
The Practical Takeaway
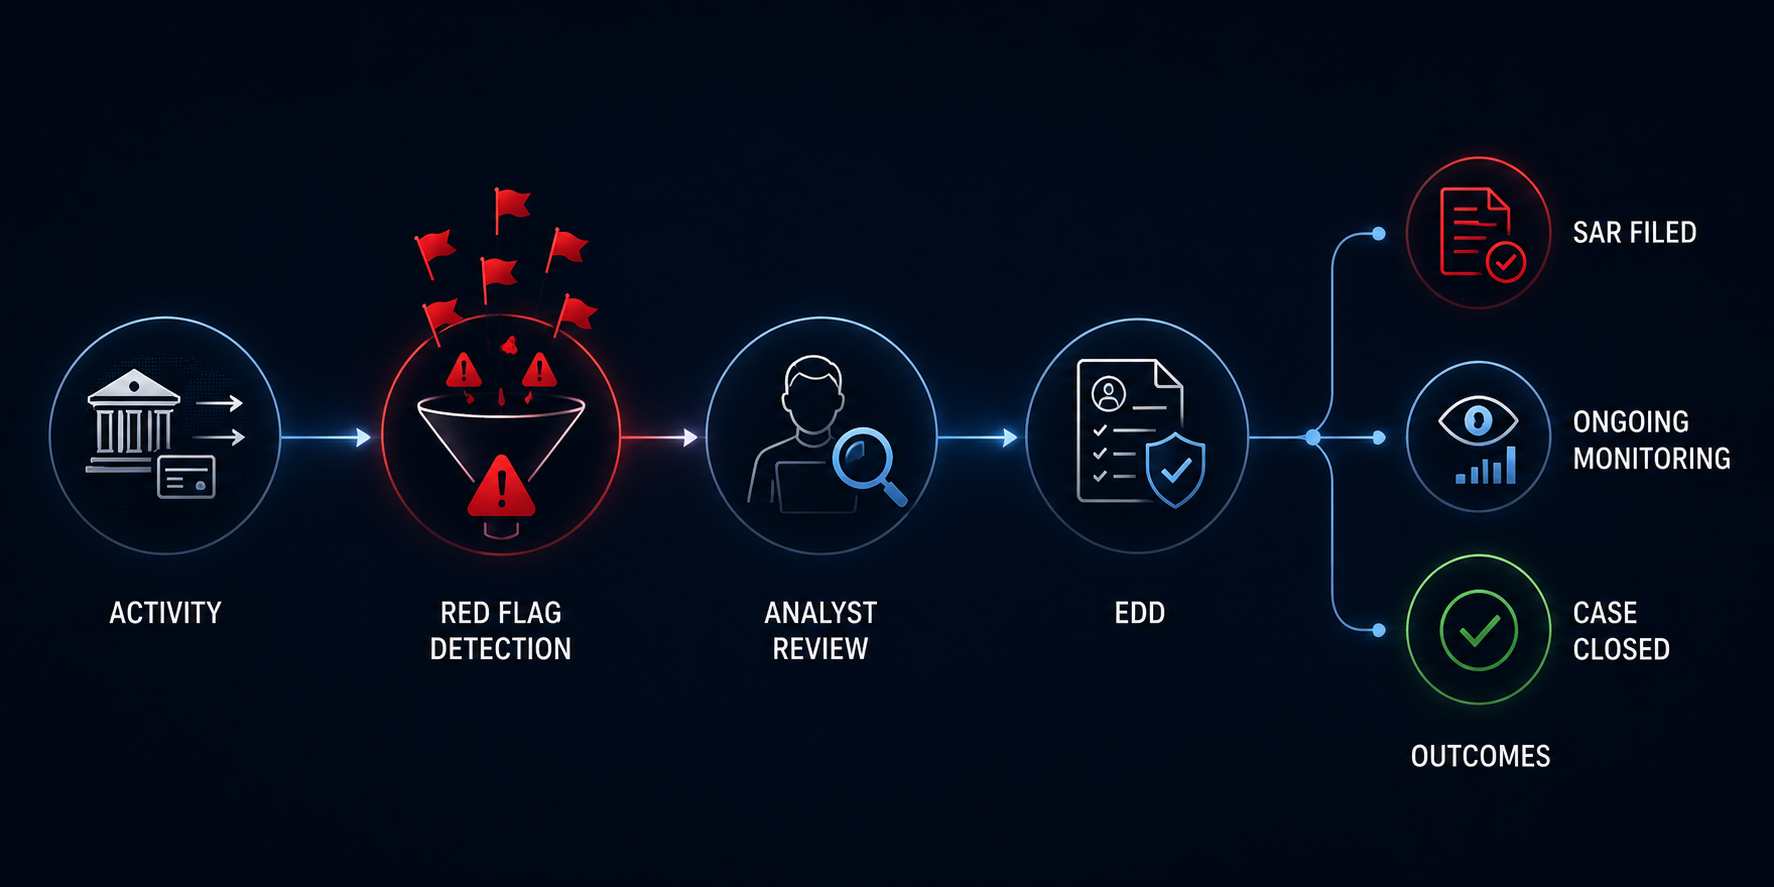
AML red flags don’t tell you what is happening. They tell you where to look. Some institutions build robust red flag monitoring and invest in the systems, training, and investigative capacity to act on what those systems surface. These institutions consistently catch financial crime earlier and file better Suspicious Activity Reports. They also build the kind of compliance record that regulators recognize as genuine effort rather than a checkbox exercise.
FATF’s standards require continuous transaction monitoring, not periodic reviews. That means ongoing analysis that compares transactions against customer risk profiles and flags deviations for investigation. Institutions that treat this as a live, active process rather than a retrospective audit are operating at the level the threat environment actually requires.
The difference between catching financial crime at the first red flag and catching it six months later is measured in more than investigative complexity. It is also measured in recoverable funds, reputational exposure, and regulatory consequence. The signals are there. The question is whether the institutions looking at them know what they’re seeing, and what to do next. Our guide to AML investigations explains how.
FAQs
What are AML red flags?
AML red flags are a signal or pattern of behavior that indicates a transaction or account warrants closer scrutiny. It does not confirm criminal activity. Instead, it identifies where enhanced due diligence is needed. Red flags are most powerful when multiple indicators align around the same account or relationship.
What happens when a financial institution identifies a red flag?
Identifying a red flag triggers a review process. Depending on the institution’s risk framework and the nature of the signal, this may involve enhanced due diligence, customer questioning, internal escalation, or the filing of a Suspicious Activity Report (SAR) with the relevant financial intelligence unit.
What is structuring, and why is it an AML red flag?
AML Red Flags in Practice
Structuring, also known as smurfing, is the practice of breaking large sums into smaller transactions that fall below mandatory reporting thresholds, specifically to avoid triggering those reports. The individual transactions may look unremarkable. The pattern of deliberate, repeated sub-threshold activity is the flag.
What is trade-based money laundering and why is it so hard to detect?
Trade-based money laundering involves disguising illicit funds within legitimate trade transactions, typically through over- or under-invoicing, false shipment documentation, or phantom shipments. It’s difficult to detect because it embeds illicit flows within high-volume, complex, cross-border trade activity. Detecting it requires cross-referencing financial data with trade documentation. Many institutions are not yet doing this systematically.
How are cryptocurrency transactions monitored for AML purposes?
Blockchain analytics tools allow institutions to screen wallet addresses against known illicit actors, trace transaction histories, and identify connections to sanctioned entities, darknet markets, or previously flagged activity. The permanent, public nature of blockchain data means that cryptocurrency transactions leave a traceable record. The tools to read that record are improving rapidly.
What is the difference between AML red flags and a Suspicious Activity Report?
AML Red Flags and Suspicious Activity Reports
AML red flags are signals that trigger review. A Suspicious Activity Report is the formal document an institution files with a financial intelligence unit. The institution files it when, after investigation, it believes a transaction or pattern of activity may involve financial crime. Not every red flag results in a SAR. However, every SAR should follow the identification and investigation of red flags.
How does CAT Investigators support financial institutions with AML?
CAT Investigators provides financial crime investigation, due diligence, and asset tracing services to financial institutions, legal teams, and compliance functions. Internal monitoring may surface AML red flags that warrant deeper investigation. This is especially true for complex corporate structures, cross-border activity, or cryptocurrency. In those cases, we provide the investigative capacity to go further than internal teams typically can. Contact us to discuss your case.