JPMorgan paid $175 million to acquire Frank, a student financial aid startup, based on a claimed user base of 4.25 million. The actual number was closer to 300,000. The gap was bridged by synthetic customer data that only came apart after the deal closed, when an email campaign built on those "users" produced delivery rates no real customer base would produce. Frank's founder, Charlie Javice, is now serving 85 months in federal prison. The red flags were there before the deal closed: inflated metrics, a story that didn't hold up under scrutiny, an audience of investigators that never actually checked. None of it was discovered in time. Not because it was particularly well hidden. Because nobody looked hard enough.
On average, companies worldwide lost 7.7% of their annual revenue to fraud over the past year. That represents an estimated $534 billion. A significant portion of that figure walks in through a signed agreement with a partner nobody properly investigated. And in most of those cases, the information that would have changed the decision was available before the ink dried. Corporate due diligence finds that information.
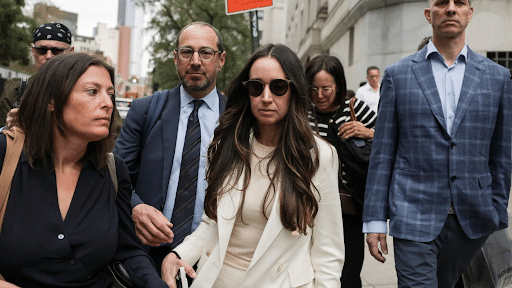
Charlie Javice leaves Manhattan federal court after being sentenced to 85 months in prison. Source: Reuters
What Corporate Due Diligence Actually Is
The Difference Between a Background Check and an Investigation
Most organizations have something they call due diligence services. Most of those processes share a fundamental limitation: they’re designed to verify, not to investigate.
A typical database check combines internally compiled research from corporate registries, court records, and regulatory filings with licensed data from external sources. These include intelligence providers, sanctions screening platforms, PEP databases, adverse media aggregators, and commercial risk intelligence services. Such a check tells you a name doesn’t appear on a sanctions list. For example, a corporate registry extract confirms a company exists. A credit report shows no obvious financial defaults. All of it confirms the surface. However, none of it tells you what’s underneath.
A clean result across all of them doesn’t mean a counterparty is clean. It means only that the sources checked hold no formal record of a problem. However, the most significant risks in a business relationship are rarely recorded anywhere. Instead, they live in undisclosed ownership structures, unregistered relationships, and the gap between what a partner presents and what a proper investigation would find.
Why Automated Screening Falls Short
The distinction matters because the most significant risks in a business relationship are rarely the ones that appear in databases. Jurisdictions with high financial secrecy hold 40% of global wealth, which necessitates deep diligence.
Hidden ownership structures, undisclosed liabilities, and regulatory exposure in other markets don’t surface through automated screening. They surface through investigation, which is exactly what corporate due diligence services deliver.
| Risk area | Automated screening | Enhanced due diligence | Field / source intelligence |
|---|---|---|---|
| Sanctions and PEP screening | High | High | Medium |
| Registry and corporate existence | High | High | Medium |
| Litigation and regulatory checks | Medium | High | Medium |
| Beneficial ownership and control | Low | High | High |
| Hidden liabilities / inflated metrics | Low | High | Medium |
| Reputation not captured in databases | Low | Medium | High |
| Cross-border contextual risk | Low | High | High |
| Source of funds / commercial rationale | Low | High | High |
What Corporate Due Diligence Requires: Knowing Who You're Dealing With
Real corporate due diligence requires treating a prospective partner the same way an investigator would treat a subject, systematically, skeptically, and with the goal of finding what isn’t immediately visible rather than confirming what is. That means going beyond documents to understand the human reality behind an entity. Ask who actually controls it. Ask what its reputation looks like from the outside. Then check whether the story it presents matches what people who’ve worked with it say privately.
The Most Common Risks That Corporate Due Diligence Surfaces
Hidden Financial Liabilities and Inflated Metrics
The Frank/JPMorgan case is the clearest recent example. JPMorgan acquired Frank for $175 million based on claimed user numbers of 4.25 million. However, the actual figure was closer to 300,000. Nobody discovered the synthetic customer data that bridged the gap until after the deal closed. Then an email campaign produced delivery rates that made the fabrication impossible to ignore. Most organizations recover 25% or less of their fraud losses. By that point, the leverage to do anything about it has largely gone. Thorough corporate fraud investigations aim to surface exactly this kind of risk before a deal closes rather than after.
Undisclosed Ownership and Shell Company Structures
Beneficial ownership is one of the most consistently underinvestigated areas in pre-deal corporate due diligence. Who legally owns an entity is rarely the same as who actually controls it. Control can be exercised through financing arrangements, advisory relationships, or informal agreements that exist entirely outside formal documentation. A layered ownership structure with no obvious commercial rationale is a finding in itself. It is also exactly where enhanced due diligence methodology helps most.
Reputational Issues That Don't Appear in Databases
A counterparty can have entirely clean regulatory records and no adverse media coverage. Yet its industry may broadly see it as an unreliable partner, a litigation risk, or an organization under financial pressure it hasn’t disclosed publicly. That intelligence doesn’t exist in any database. Instead, it exists in conversations with people who’ve worked with them, invested alongside them, or left the organization. Getting to it requires the kind of field investigation that distinguishes genuine corporate investigations from a standard compliance screening exercise.
Sanctions and Regulatory Exposure Across Jurisdictions
A counterparty that looks clean in its home market may carry significant exposure in others. Compliance standards vary significantly across jurisdictions, and enforcement culture doesn’t always match what’s written in law. Thorough corporate due diligence services check the entity’s regulatory standing across every market where it operates. They do not stop at the one where the parties sign the deal.
The Red Flags Most People Rationalize Away
The pattern that comes up repeatedly in corporate fraud investigations that end in litigation is not that the red flags were invisible. It’s that they were visible and explained away.
Reluctance to share documentation is the clearest signal. Any legitimate business has financial records, corporate filings, and legal history it can provide on request. Evasiveness, shifting answers, or a pattern of providing summaries instead of underlying records are not minor friction. They’re information.
Pressure to move fast is rarely accidental. Creating urgency is a familiar tactic for preventing the scrutiny that a slower process would enable. A genuine opportunity doesn’t disappear because a buyer takes the time to verify what they’re buying.
References that are hard to verify independently are worth a closer look on their own. So are ownership structures layered without identifiable commercial purpose. The same goes for a pitch that’s significantly more impressive than the counterparty’s actual industry reputation. Together, they form a pattern that enhanced due diligence specifically examines.
The Human Intelligence Layer of Corporate Due Diligence
What Field Investigation Finds That Document Review Doesn't
The most significant findings in a corporate due diligence engagement rarely come from documents. Instead, they come from conversations.
Specifically, source interviews involve reaching the people who have worked with a counterparty, invested alongside them, or left their organization. Their perspective will never appear in a database. They also won’t appear on a reference list the counterparty provides itself. Getting to them requires investigative methodology: knowing who to look for, how to approach them, and what to ask.
On-the-Ground Research in International Jurisdictions
In cross-border transactions, remote desktop research has real limits. Some information is simply not available any other way. It comes only from in-person field investigation in the relevant jurisdiction, conducted in the local language with local knowledge and local contacts. The most consequential findings in international corporate investigations tend to come from this layer, not from databases.
When to Commission Corporate Due Diligence
The window for the most valuable pre-deal investigation closes earlier than most people expect.
Once the parties sign a term sheet and set a timeline, the investigative process operates under commercial pressure. That pressure constrains both its scope and its findings. Sources are harder to approach when the relationship is already publicly known. Findings that would have changed the negotiating position at an earlier stage become harder to act on once the parties have made commitments.
Due diligence services are also not only useful as a reason to walk away. Parties frequently use investigation findings as the basis for renegotiation. They adjust valuation, require remediation as a condition of proceeding, or structure additional protections into the deal. The corporate due diligence process in mergers and acquisitions exposes hidden liabilities that can shift the terms of a deal significantly. However, that only works if the investigation happens early enough. Then the findings serve as leverage rather than as grounds for litigation after the fact.
What a Proper Corporate Due Diligence Report Delivers
The deliverable from a properly conducted corporate due diligence engagement is not a list of database results. It’s a structured intelligence report. It documents what we know, what remains uncertain, what requires further examination, and what the risk implications are for the specific transaction under consideration.
That means verified facts with sources, not database outputs without context. Risk implications specific to the deal, not generic categories of exposure. And an honest account of what remains uncertain and what it would take to close that gap. That account is often as useful as the confirmed findings, because it tells a decision-maker where they’re still operating without full information.
A database check that comes back clean documents only that it found no obvious issues. Thorough corporate due diligence services document what the picture actually looks like including the parts that weren’t in any database.
A Handshake Is Not Corporate Due Diligence
The partnerships that end in fraud, litigation, or significant financial loss almost always had warning signs. The question that consistently goes unanswered isn’t whether those signs existed. It’s whether anyone looked for them in the right places, using the right methodology, before making the decision.
A LinkedIn profile and a strong pitch are not corporate due diligence. Neither is a database check that comes back clean. In high-value decisions, the cost of not knowing is almost always higher than the cost of finding out.
If you’re approaching a significant partnership, acquisition, or commercial relationship, you may want to understand what a proper pre-deal investigation would cover. The first conversation is confidential.
FAQs
What is corporate due diligence?
Corporate due diligence is the structured process of investigating a potential business partner, counterparty, or acquisition target before entering a commercial relationship. It goes beyond standard screening to examine beneficial ownership, financial health, litigation history, reputational standing, and cross-border exposure. The result is a verified picture of who you’re actually dealing with rather than confirmation that a name comes back clean. Professional corporate due diligence services combine forensic analysis, field investigation, and source intelligence to surface what automated tools consistently miss.
When should due diligence be commissioned?
As early as possible. The most valuable corporate due diligence work happens before the parties sign a term sheet and set a deal timeline. Once commercial pressure is in place, it constrains the scope and findings of an investigation. Therefore, early engagement produces findings that can be used as negotiating leverage, not just as grounds for walking away.
What does a due diligence investigation include?
What Does Corporate Due Diligence Cover?
A thorough corporate due diligence investigation covers:
- Financial health beyond headline numbers, including undisclosed liabilities.
- Corporate structure and beneficial ownership.
- Litigation and regulatory history across all relevant jurisdictions.
- Reputational intelligence from source interviews and field investigation.
- Sanctions and adverse media screening.
Where a counterparty presents elevated risk, enhanced due diligence adds deeper scrutiny of source of funds, beneficial ownership through multiple layers, and cross-border regulatory exposure.
What red flags does due diligence typically uncover?
The most common findings in corporate fraud investigations include:
- Undisclosed beneficial ownership or hidden control structures.
- Financial representations that don’t survive forensic scrutiny.
- Corporate structures layered without commercial rationale.
- Reputational issues well known in the industry but absent from formal records.
- Litigation history that wasn’t volunteered during the commercial process.
How long does corporate due diligence take?
A focused review can be completed in one to two weeks. A full cross-border corporate due diligence investigation involving beneficial ownership tracing, source interviews, and international records can take several weeks to a few months. The timeline depends on the jurisdictions involved and the depth of the matter.
Can due diligence findings be used in legal proceedings?
Yes, provided the corporate investigations were conducted and documented to evidentiary standards. Findings that identify specific misrepresentations, undisclosed liabilities, or fraudulent disclosures can support renegotiation, contract claims, regulatory submissions, and civil litigation. The standard of documentation matters as much as the findings themselves.
How does CAT Investigators approach corporate due diligence?
Why Choose CAT Investigators?
CAT Investigators provides specialist corporate due diligence services. They combine forensic financial analysis, corporate structure mapping, beneficial ownership tracing, blockchain forensics where digital assets play a role, and field intelligence from source interviews and on-the-ground research in relevant jurisdictions. Our enhanced due diligence capability covers high-risk counterparties, cross-border transactions, and situations where standard screening has already reached its limits. We deliver our corporate investigations and corporate fraud investigations as structured intelligence reports. These reports aim to inform decisions, not simply to document that someone followed a process. With offices in New York, London, and Hong Kong, we work across the markets where clients make their most significant decisions.
Sources
- H2 2025 Global Fraud Report: Companies Worldwide Lost 7.7% of Annual Revenue to Fraud
- Due Diligence Industry Statistics 2026: 40% of Global Wealth Held in High Financial Secrecy Jurisdictions
- U.S. Department of Justice: Startup CEO Charlie Javice Sentenced to 85 Months in Prison for $175 Million Fraud (Frank/JPMorgan Case)
- 2025 Fraud Investigation Benchmark Report: Most Organizations Recover 25% or Less of Fraud Losses
- Fraud Losses by Sector 2024: Statistics and Trends